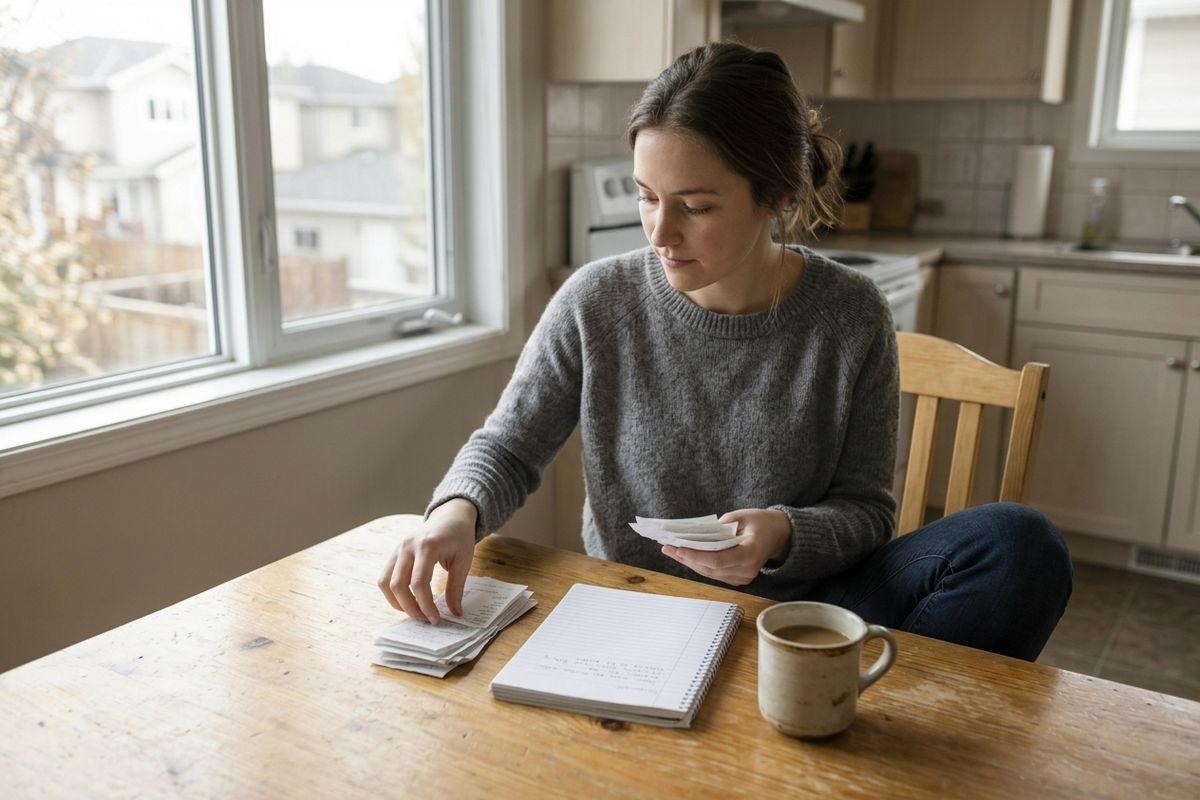
That guessing game gets old fast, and it can leave you feeling stuck.
Payday rolls around, and before your next paycheque arrives, the money can feel like it slipped through your fingers. You’re not sure where it went, and the same worry shows up every month. That guessing game gets old fast, and it can leave you feeling stuck.
To make a budget, add up your monthly after-tax income, list your fixed and flexible expenses, then set clear spending limits so every dollar has a job. Once you see the full picture, you can plan for bills, save a little each month, and stop wondering where your cash disappeared.
Why a Budget Matters for Your Money
A budget is just a plan for the money coming in and going out. When you write it down, spending stops being a mystery. You can see the coffee runs, the streaming services, and the grocery trips all in one place.
That clear view helps you make smarter choices day to day. A good budget can help you in a few ways.
- Track where your money goes each month
- Plan ahead for bills and savings
- Build steady financial habits that stick
Over time, these small habits add up. You might notice extra room for a rainy-day fund or a little breathing space before your next paycheque lands.
Steps to Set Up Your First Budget
Starting a budget feels easier when you break it into three simple steps. Grab a notebook or a free app, and work through them one at a time.
- Add up your monthly income
- List your fixed and flexible expenses
- Set clear spending limits for each category
Track Your Income
Write down every source of money you get in a month. This gives you a real number to build around:
- Paycheques, side work, and other sources like tips or benefits
- Use after-tax amounts, since that’s what actually reaches your bank account
Using take-home pay keeps your plan honest. If you budget with the bigger pre-tax number, the math falls apart quickly.
Sort Your Spending
Next, sort your spending into needs and wants, then set aside money for longer-term goals. This helps you spot where you can cut back while still making progress toward what matters to you:
- Needs like rent, groceries, and utility bills
- Wants like dining out, hobbies, and subscriptions
- Long-term goals like a down payment on a home, a vacation, or an emergency fund
Seeing the two side by side makes trade-offs clear. You can keep the wants that matter most and trim the ones you barely notice.
Budget Methods That Fit Your Life
There are several common ways to budget. The trick is picking a method you’ll actually use. Here are three approaches to consider:
- The 50/30/20 rule splits income into needs, wants, and savings for a simple starting point
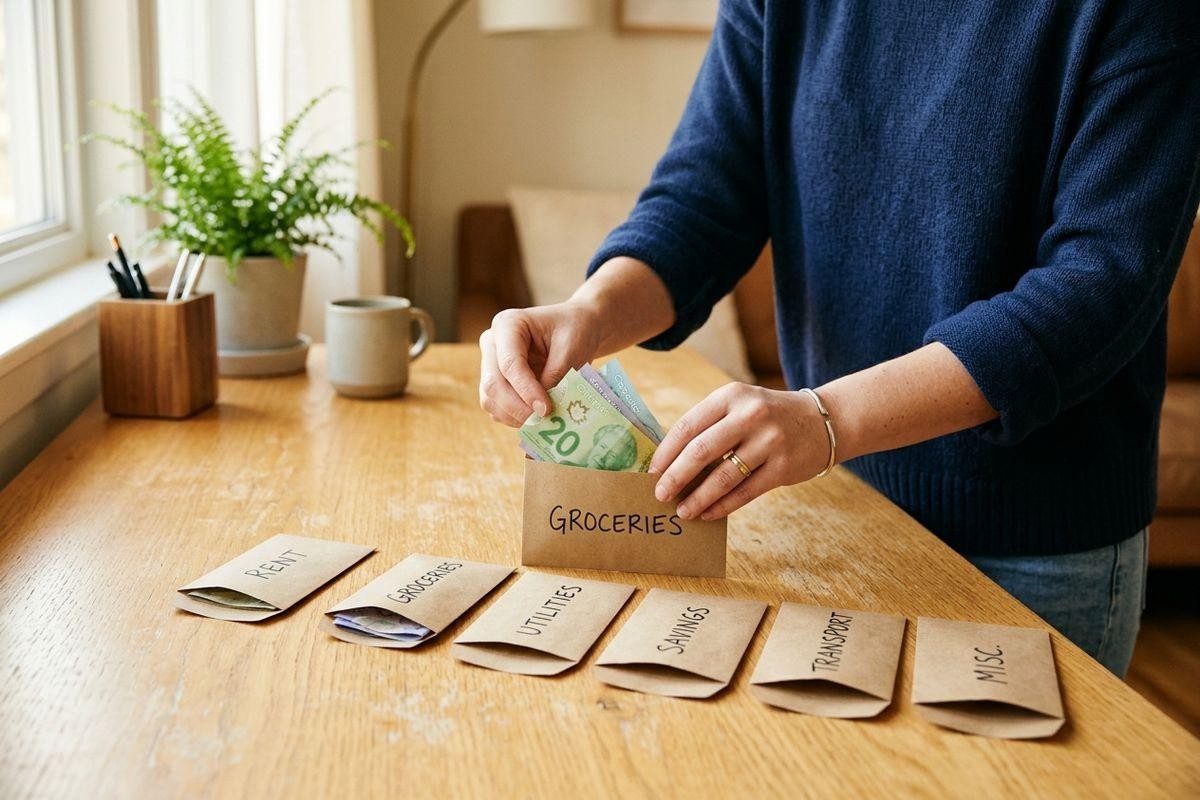
- The envelope method sets aside cash for each category, which helps if you overspend on cards
- A zero-based plan gives every dollar a job, so nothing slips away unnoticed
Pick What Feels Doable
The right method is the one that matches how you already live. If you love simple math, the 50/30/20 rule fits nicely. If you spend cash and want a hands-on feel, envelopes might click better for you.
Your needs change over time, so your budget can too. Review it after a raise, a move, or a new baby, and adjust the numbers to fit your life today.
How Loans Fit Into a Healthy Budget
Sometimes a planned expense is bigger than what your monthly budget can cover. A car repair, a dental bill, or a slow month at work can throw things off. A loan may be one option, but the repayment still needs to fit your budget.
The key is knowing how the repayment fits before you borrow. A loan may be one option when a planned expense is larger than your budget, but the payments still need to fit your finances. Blue Copper Capital offers personal loan options in Alberta. BC borrowers can ask about the installment loan and line-of-credit products available to them.
Borrow With a Clear Plan
Short-term loans may be one option for costs you need to cover quickly. Before borrowing, make sure the repayment fits your budget.
Before signing, ask the lender to explain the terms in plain language. The team gets to know the person behind the application and walks you through every detail, so you understand what you’re agreeing to.
Support for Small Business Owners
Cash flow gaps happen to almost every small business. A slow season or a late invoice can leave you short when payroll is due.
Business loans may help cover those gaps and keep things moving, but the repayment still needs to fit the business’s budget.
Common Budget Questions Answered
A few questions come up again and again once people start budgeting. Here are quick, clear answers to help you keep going.
How Often Should You Review It?
Check your budget once a month to compare what you planned against what you spent. Small tweaks each month keep the plan realistic.
Update it after big life changes too. A new job, a move, or a growing family can shift your numbers fast, so your budget should shift with them.
What if Money Gets Tight?
When funds run low, start by trimming flexible spending like dining out and subscriptions. Those cuts are usually the quickest to make and the easiest to reverse later.
If you still come up short for a planned cost, you can explore short-term loan options in Alberta. Borrow only what fits your budget, and understand the terms before you sign.
A budget can help you decide whether borrowing makes sense. Blue Copper Capital can explain available options and the terms before you commit. Begin your application online, give the team a call, or visit our Calgary or Edmonton office if you’re in Alberta to talk through flexible loan options that may fit your situation. If you’re in BC, use the online or phone options to ask what may be available.